Faster turn times. Proven reliability. Ready for UAD 3.6.
UAD 3.6 is adding days to appraisal turn times industry-wide with appraisers now required to capture more property data on-site. Our hybrid data collection process already meets that standard. The result: valuations two to three days faster, with more than 90% of loans now eligible for hybrid under the new requirements.
There’s never been a better time to make hybrid appraisals part of your standard order. Fill out the form to talk to a hybrid specialist.
Traditional appraisals are taking longer. UAD 3.6 requires more detailed, room-by-room documentation on every inspection,including interior and exterior condition, measurements, and a standardized dataset for the new report format. Our hybrid data collection process already meets that documentation standard, so hybrid orders skip the added time entirely. It’s the same process we’ve been running for years, now caught up to by the rest of the industry.
Our Hybrid Appraisals by the numbers
2-3 days
faster turn time vs traditional appraisal
+90% of loans
are eligible for a hybrid under UAD 3.6
67% of ROVs
resulted in no change to the original opinion of value, same as any appraisal
Costs less
than a UAD 3.6 traditional appraisal
How our Hybrid Appraisal works
1
Data collection
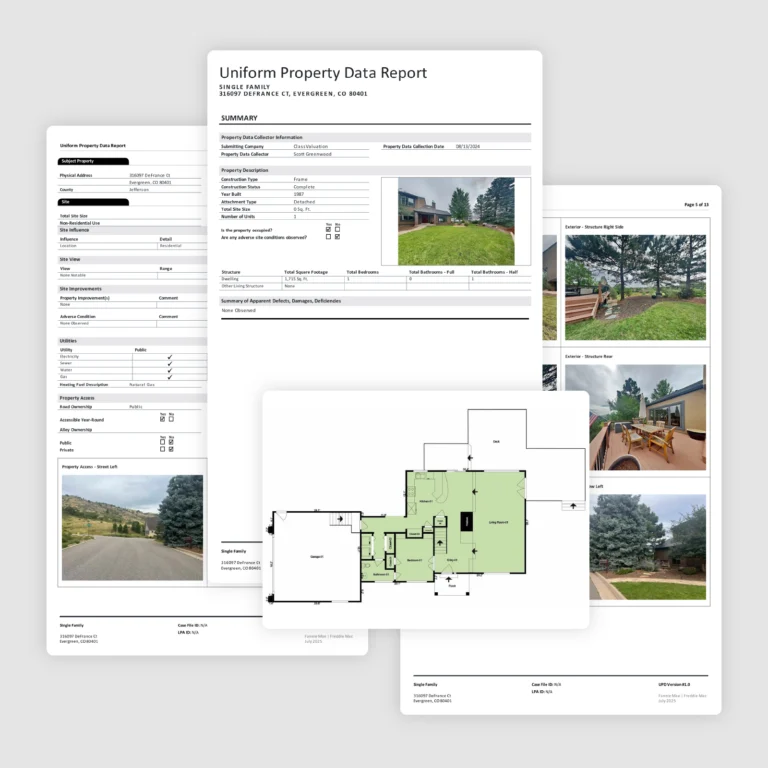
A trained property data collector visits the property and captures the standardized data set: interior and exterior condition, room measurements, and floor plan.
2
GSE validation
The Property Data Report is submitted to and validated by Fannie Mae or Freddie Mac, catching issues like a missing room or incomplete data before the appraisal moves forward.
3
Appraiser review and reporting
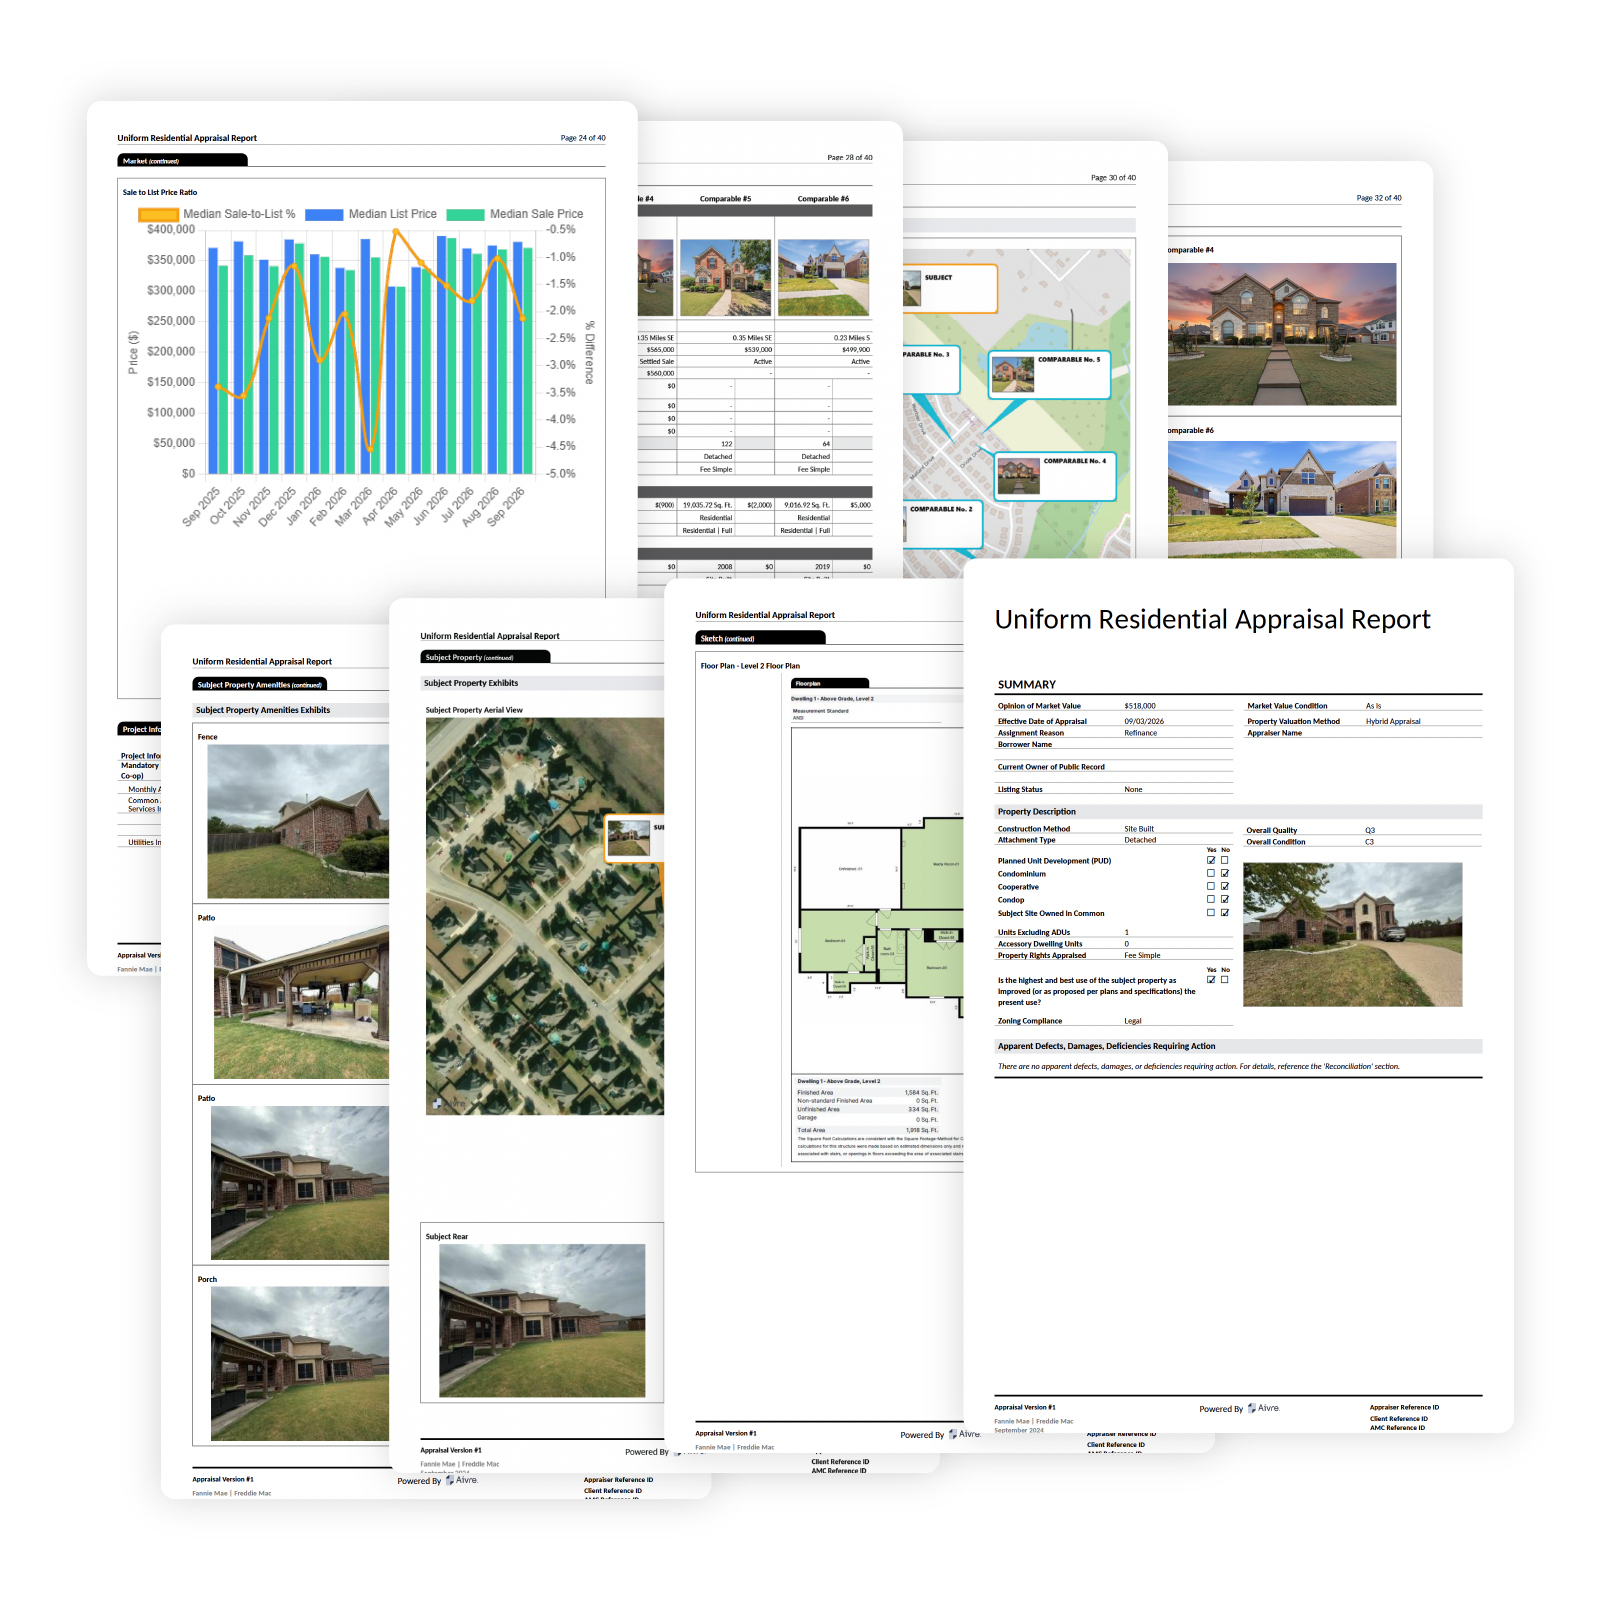
The property data is passed to the appraiser, who uses their expertise to give an Opinion of Value based on the structured data. The appraiser completes the UAD 3.6 report.
4
Report delivered
The completed UAD 3.6 report is delivered to you two to three days faster than a traditional appraisal, with consistent data and no discrepancies to sort out.
Property Data Collection
Every inspection, held to the UAD 3.6 standard
One of the largest pools of property data collectors in the industry, with over 65,000 property data collection reports completed, all capturing the detail UAD 3.6 requires.
Data collectors complete GSE and internal training, plus background checks.
Floor plans are ANSI compliant. Data collection follows a standardized process that satisfies UAD 3.6 requirements.
Property Data Report clears GSE validation before the appraisal is completed.
The Property Data Report is reviewed by the appraiser, who develops the independent Opinion of Value.
Are hybrids less reliable since there's less time on site?
No. Our data collection process is standardized to strict specifications. Data collection tends to surface more about a property’s condition, not less, compared to a typical walkthrough.
Does a hybrid appraisal still hold up the same way a traditional one does?
Yes. Every hybrid appraisal still results in a fully developed, independently supported opinion of value. The process changes. The standard it’s held to doesn’t.
How is the appraiser involved in a hybrid?
The appraiser reviews the Property Data Report, researches comparables, and develops the opinion of value. If something in the data doesn’t match their judgment, they can flag it and explain why. Their independence and expertise don’t go away in a hybrid.
How much faster is a hybrid appraisal, and are more orders eligible for UAD 3.6?
On average, hybrids save two to three days in turn time compared to a traditional appraisal. With UAD 3.6, hybrid eligibility has also climbed to ~90% of loans.
Is every order eligible for a hybrid?
No. Complex properties, large acreage, or reviewer judgment can call for an upgrade to a traditional appraisal. When that happens, we let you know fast, typically within two hours of the order coming in.
Can a hybrid be upgraded to a traditional appraisal?
Yes. If the appraiser determines they need to see the property in person, the order can be upgraded to a traditional appraisal. This happens rarely. In most cases, we catch this before the Property Data Report even reaches the appraiser, so you’re not waiting on a review cycle before the upgrade decision is made. We have a defined upgrade process in place and are happy to walk you through it.
Ready to try a Hybrid Appraisal?
Talk to a specialist about adding hybrid appraisals to your orders: what’s eligible, pricing, and how to get started before the UAD 3.6 mandate hits. Our team will help you make the move with confidence.