UAD 3.6 brings new data elements, inspection criteria, and report format, and everyone is building familiarity at the same time. Our hybrid appraisals are a known path through it: a standardized, validated process where each assignment arrives organized in the new format. Valuations are often two to three days faster, and more than 90% of loans are now eligible for hybrid.
Make the switch to UAD 3.6 easier. Fill out the form to talk to a specialist.
UAD 3.6 asks for more detailed, room-by-room documentation on every inspection, including interior and exterior condition, measurements, and a standardized dataset for the new report format. Our hybrid data collection process already follows that documentation standard, so each hybrid assignment arrives organized in the new format. It’s the same standardized process we’ve been running for years, and you order it the same way you order today.
faster turn time vs a UAD 3.6 traditional appraisal
are eligible for a hybrid under UAD 3.6
resulted in no change to the original opinion of value
than a UAD 3.6 traditional appraisal
A standardized property data collection process that meets UAD 3.6 requirements, validated by Fannie Mae or Freddie Mac up front.
Same ordering process you already use, with no new workflow to build. Each hybrid assignment arrives organized in the UAD 3.6 format.
A licensed appraiser still forms the independent opinion of value, backed by nationwide coverage and a service-led team on every order.
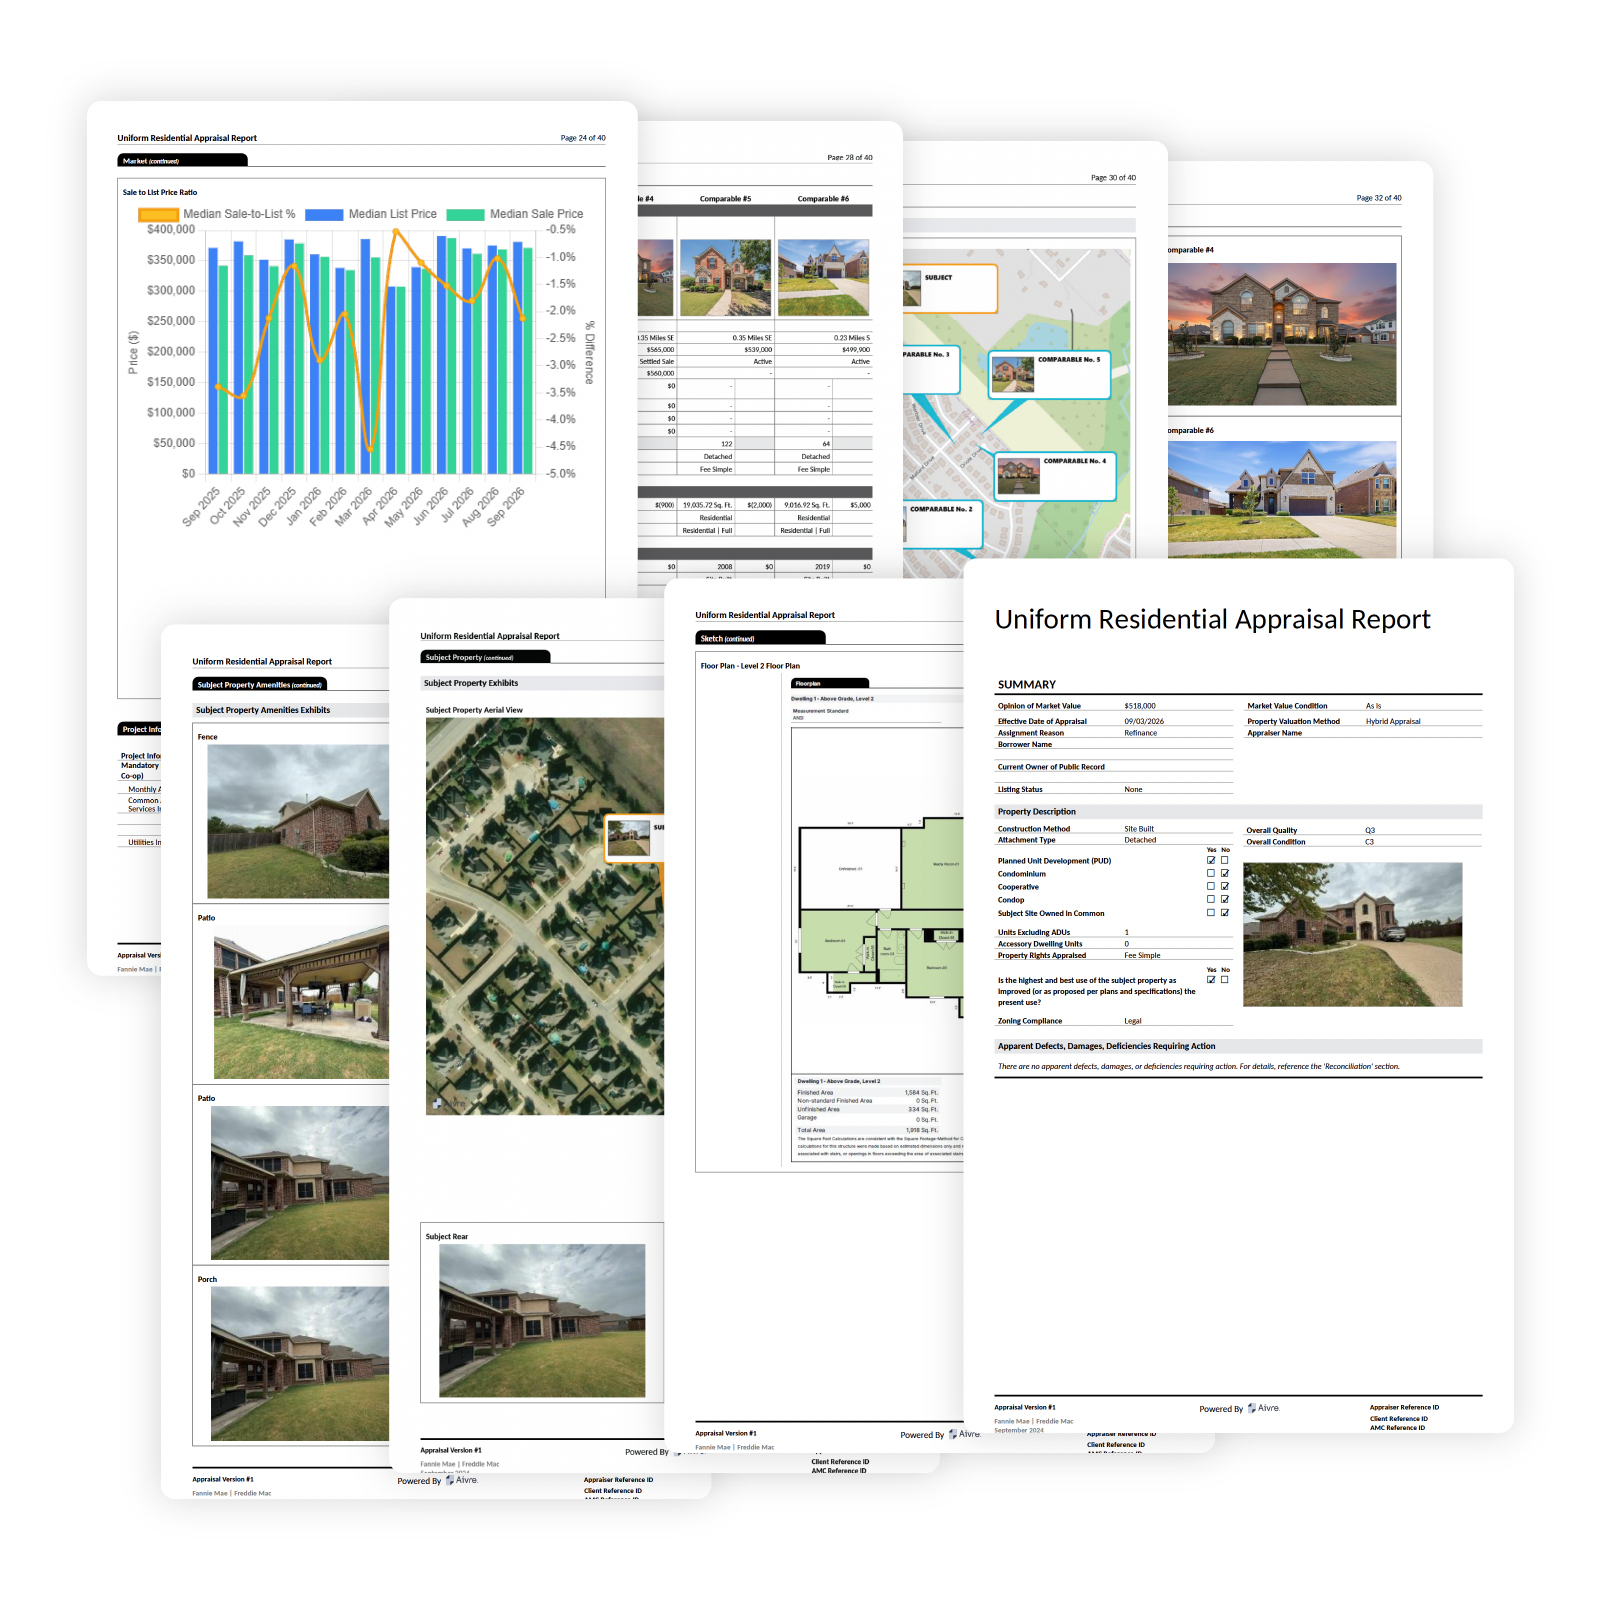
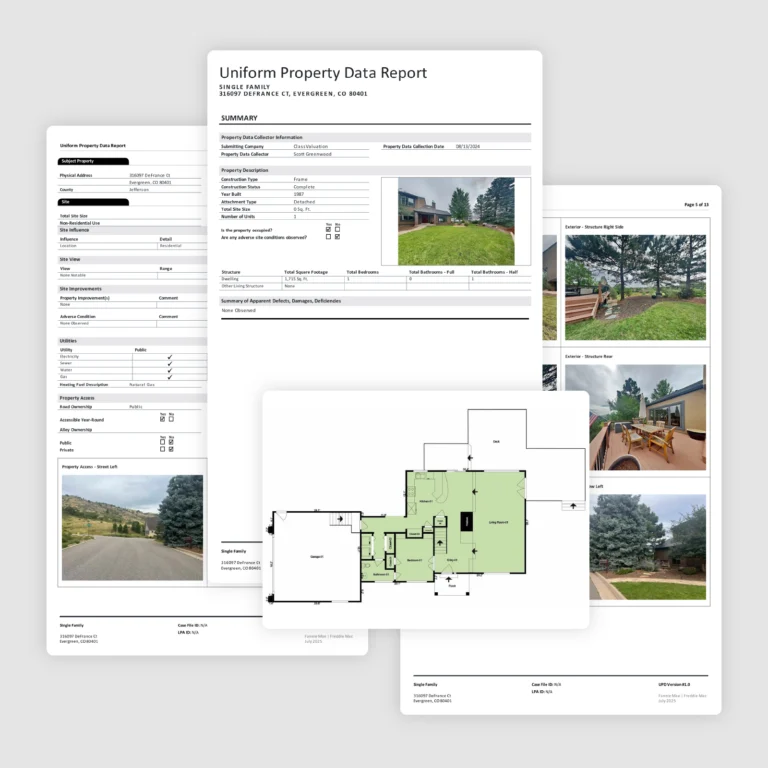
A trained property data collector visits the property and captures the standardized data set: interior and exterior condition, room measurements, and floor plan.
The Property Data Report is submitted to and validated by Fannie Mae or Freddie Mac, catching issues like a missing room or incomplete data before the appraisal moves forward.
The property data is passed to the appraiser, who uses their expertise to give an Opinion of Value based on the structured data. The appraiser completes the UAD 3.6 report.
The completed UAD 3.6 report is delivered to you often two to three days faster than a traditional appraisal, with consistent data and no discrepancies to sort out.
Over 65,000 Property Data Collection (PDC) Reports completed, all capturing the detail UAD 3.6 requires.
Download a one-page overview to share with your team, then dig into the facts on reliability and what UAD 3.6 means for the inspection.
No. Our data collection process is standardized to strict specifications. Data collection tends to surface more about a property’s condition, not less, compared to a typical walkthrough.
Yes. Every hybrid appraisal still results in a fully developed, independently supported opinion of value. The process changes. The standard it’s held to doesn’t.
The appraiser reviews the Property Data Report, researches comparables, and develops the opinion of value. If something in the data doesn’t match their judgment, they can flag it and explain why. Their independence and expertise don’t go away in a hybrid.
Our hybrid appraisals are often two to three days faster than a traditional appraisal depending on the market and the order. With UAD 3.6, hybrid eligibility has also climbed to more than 90% of loans.
No. Complex properties, large acreage, or reviewer judgment can call for an upgrade to a traditional appraisal. When that happens, we let you know fast, typically within two hours of the order coming in.
Yes. If the appraiser determines they need to see the property in person, the order can be upgraded to a traditional appraisal. About 10% of hybrid orders are upgraded. In most cases, we catch this before the Property Data Report even reaches the appraiser, so you’re not waiting on a review cycle before the upgrade decision is made. We have a defined upgrade process in place and are happy to walk you through it.
The same way you order today. Choose hybrid on eligible orders, and we handle the data collection, GSE validation, and the appraiser’s review. There is no new workflow to build.
The November 2 mandate has not changed, and appraisers and AMCs deliver UAD 3.6 either way. We support both UAD 2.6 and UAD 3.6 today, on whatever timeline each client needs, and hybrid is a practical way to get hands-on with UAD 3.6 now.
Talk to a specialist about adding hybrid appraisals to your orders: what’s eligible, pricing, and how to get started before the UAD 3.6 mandate hits. Our team will help you make the move with confidence.

Join our community of lenders & brokers

Check the status of your appraisal

Request your appraisal